The key ideas
- RWA is a broad category, not a single type of token or a quality rating.
- The digital record and the underlying asset need a documented connection.
- Custody, valuation, reporting and redemption each deserve separate questions.
Real-world assets, often shortened to RWAs in crypto discussions, are assets or claims outside the blockchain that are represented through tokens. The category can include interests connected to property, financial instruments or commodities. The useful question is not only what the asset is, but how the token relates to it.
Two projects can use the same RWA label while giving their holders very different rights. Treat the label as a starting point for research. It tells you to look beyond the token contract and inspect the arrangement behind it.
The asset and its digital representation
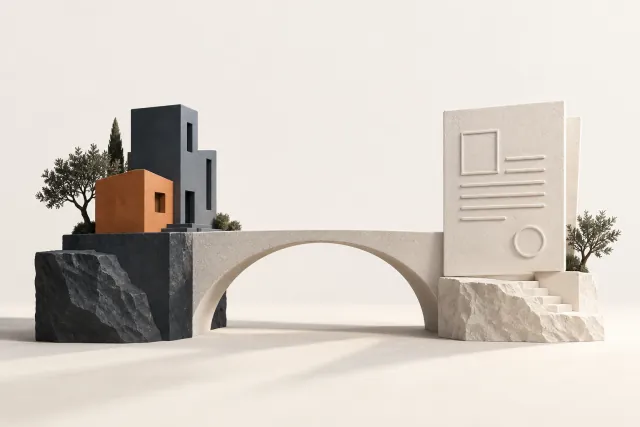
Picture a physical asset, the records describing it, and a token system tracking a particular interest. These are three distinct layers. A digital record does not transport the asset onto a blockchain; it represents something about it.
A good project explanation makes the connection explicit. It identifies the relevant asset or pool, who controls it, what holders can claim and which records support those statements. Without that connection, a token may carry an attractive description without establishing the expected exposure.
Reference: BIS — Financial stability implications of tokenisation ↗
Why the RWA category contains different models
A commodity-related token might depend on storage and custody. A token linked to receivables might depend on collection and the creditworthiness of a payer. A property-related token might depend on title, a holding entity, management arrangements and the way expenses are allocated.
These are illustrative models, not a complete taxonomy. They show why a checklist designed for one asset cannot simply be copied to another. The failure of a custodian, a missed payment and a vacant property create different practical problems.
Trace four connections
When reading a proposal, draw a line from the token to the asset and mark every organization in between. Then ask what happens at each connection. This small exercise can reveal where an apparently simple product depends on several separate promises.
- Control: who holds the asset, and who can direct its sale or use?
- Measurement: how is value calculated, by whom and on what date?
- Reporting: how are changes communicated and reconciled with token records?
- Exit: is there a documented redemption route, a secondary transfer route, or neither?
Read redemption and trading separately
Redemption means exercising a right against an issuer or arrangement under stated conditions. Trading means finding another party willing and able to take your position. A proposal should explain which route exists and what costs, eligibility checks, limits or delays apply.
Consider a fictional token that can be transferred between approved holders but cannot be redeemed on demand. Its transferability does not create an obligation for the issuer to buy it back. This distinction matters especially when the underlying asset itself is slow to sell.
Where Kyros fits into the discussion
Kyros explores a proposed connection between real estate in Ras Al Khaimah and blockchain-based participation. That places its stated vision within the wider RWA conversation. It does not, by itself, verify a completed tokenized asset structure.
Use the project’s disclosures to separate the regional thesis from asset-specific records. If a document has not been supplied, record the question as unresolved. A precise account of what is known is more useful than treating an RWA label as proof of backing.
Reference: Kyros — Project disclosures ↗
Common questions
Are all RWA tokens backed in the same way?
No. The asset, issuer, custody arrangement and holder rights can differ substantially. The word “backed” needs a precise explanation and supporting records.
Can an RWA token have a price different from the asset value?
Yes. Trading conditions, fees, liabilities, rights and restrictions can produce a difference. An asset valuation and an executable token sale price answer different questions.
Sources & further reading
Source links provide technical or project context. Examples and reading checklists are editorial explanations.